Recover eligible transactions
Turn selected insufficient-funds moments into completed essential purchases instead of lost checkout events.
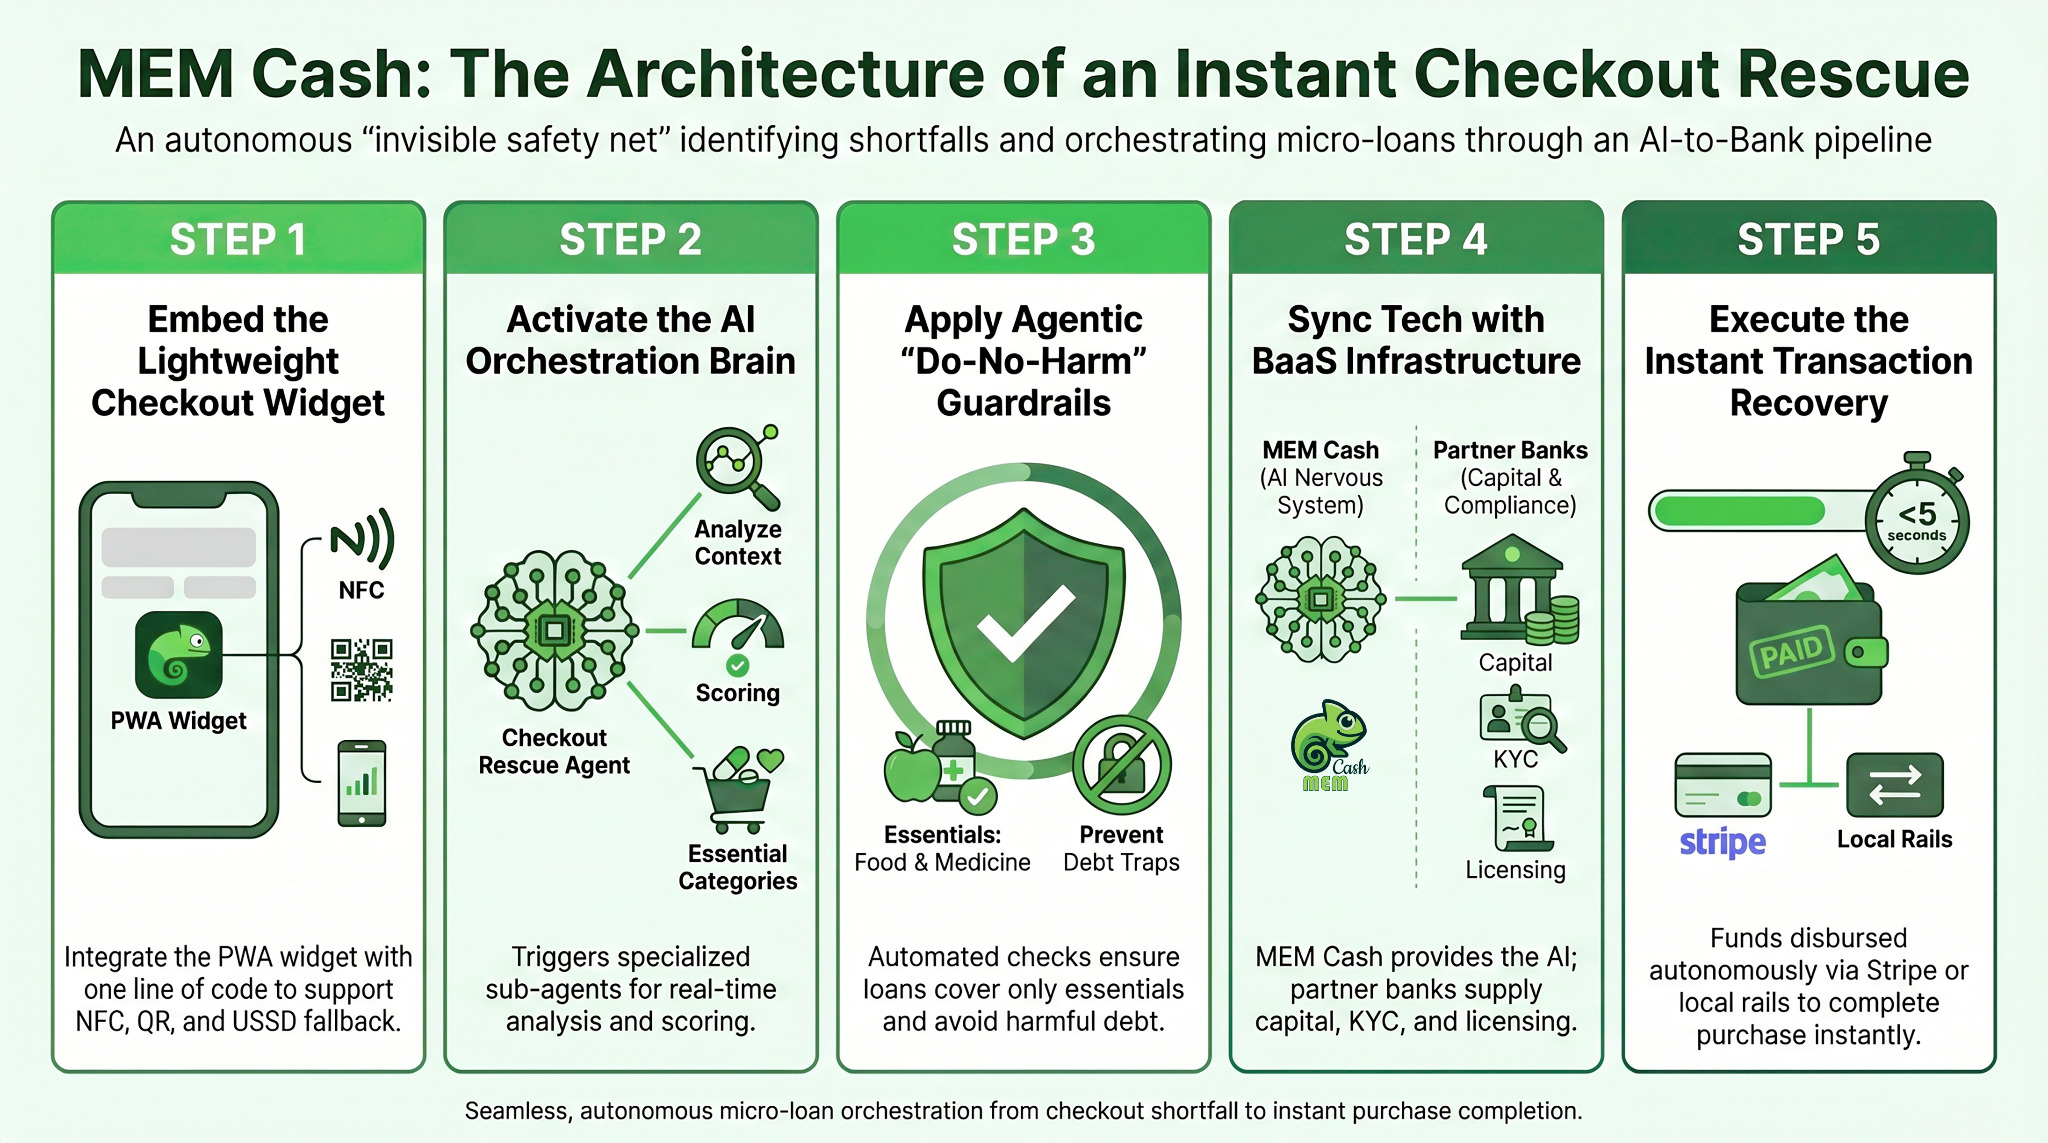
MEM Cash is designed to provide the AI orchestration, checkout integration and responsible-finance logic. Licensed financial partners retain control of capital, regulatory obligations, credit policy and risk.
Pre-seed · Functional technical prototype · Pilot pathway in Europe
The opportunity is not to replace a bank's lending infrastructure. It is to add an intelligent, narrowly scoped rescue layer at the moment a small shortfall would otherwise stop an essential purchase.
Turn selected insufficient-funds moments into completed essential purchases instead of lost checkout events.
Alternative signals and lightweight digital access can support customers who are thin-file, underbanked or poorly served by conventional products.
The partner keeps the regulated lending relationship, capital, final credit policy, KYC/AML framework and risk ownership.
MEM Cash is the technology and orchestration layer. The financial institution remains the regulated financial actor.
Technology designed to make the checkout rescue fast, narrow and explainable.
The regulated foundation that determines whether and how credit is actually extended.
The service fee is localized by market and remains fixed for the transaction rather than increasing with the size of the shortfall. This keeps the commercial incentive aligned with solving the payment problem — not with pushing a larger debt amount.
The ≈95% figure describes transaction-level technical economics before funding cost, credit losses, partner economics, customer acquisition, broader operating expenses, taxes and other market-specific costs.
MEM Cash is designed so that the core checkout rescue trigger can originate through the payment-processing layer. Open Banking can strengthen the system where available, but the product should not depend on European Open Banking infrastructure in order to exist.
The public architecture deliberately shows the partnership boundary without exposing proprietary orchestration, fraud or repayment logic.
Each partner environment will require its own legal, risk, processor and product configuration. The pathway below is therefore a framework, not a promise of automatic deployment.
We are looking for banks, MFIs, payment providers and regulated financial partners willing to explore a tightly scoped pilot for essential checkout shortfalls.